Equity release and lifetime mortgages.
A way for homeowners aged 55 and over to release money from their home. It is also a major, long-term decision that reduces what you leave behind and can affect your benefits. One of our qualified FCA-approved partners will guide you through the process and application, and provide advice and recommendations.
What is equity release?
Equity release lets homeowners aged 55 and over access some of the value tied up in their home as tax-free cash, without moving out. Fifty-five is the usual starting point rather than a guarantee: minimum age, property type, property value and how much can be borrowed all vary by lender and by applicant. The most common type is a lifetime mortgage: a loan secured on your home that is not usually repaid until you die or move into long-term care.
That is the definition. What follows is what it actually means for you, including the parts the advertising tends to play down.
What we give you on this page is straight general information, so that when you do speak to an adviser you already understand the shape of the decision. Our qualified FCA-regulated partners will guide you through the available options and, where appropriate, recommend a suitable product based on your circumstances and requirements.
Nothing on this page is advice, a recommendation, or an offer of a regulated product. It is general information about how equity release works.
How does a lifetime mortgage work?
You borrow against your home. You keep living there and you remain the owner. Interest is charged on the loan, and unless you choose to make payments, that interest is added to the loan and then itself charged interest. It compounds. The loan plus the rolled-up interest is repaid, usually out of the sale of your home, when you die or move into permanent care.
Because the interest compounds, the amount owed can grow quickly. Depending on the rate and how long the loan runs, the balance can roughly double over about fifteen years, and keep growing after that. This single mechanic is the most important thing to understand about equity release, and it is explained in full further down.
There are variants. A drawdown lifetime mortgage lets you take money in stages rather than all at once, so interest only starts running on what you have actually taken. Some products allow voluntary payments so the balance does not roll up, or roll up as fast. Which of these suits you, if any, is exactly the sort of thing a regulated adviser is there to work out.
The risks you must understand.
These come before anything good about equity release, on purpose. If a page about this product leads with the cash and buries the consequences, it is not being straight with you.
- It reduces what you leave behind. Equity release reduces the value of your estate. Money your family might have inherited from your home goes instead, in large part, to repaying the loan and its compounded interest. For many people this is the whole decision.
- The debt grows, often faster than people expect. With interest rolling up, what you owe can grow substantially over time. Release money early in retirement and the compounding has longer to run.
- It can affect your benefits. Releasing cash can affect your entitlement to means-tested benefits, such as Pension Credit or Council Tax Support, because you may then hold more in savings.
- It is expensive to unwind. Early repayment charges on lifetime mortgages can be significant. This is not a decision that is easy to reverse if you change your mind.
- It may limit your future options. Taking equity release now may reduce or remove your ability to borrow against your home later, or to move.
- It affects your family, so involve them. Because it changes what you can leave, it is generally worth involving a trusted family member or friend in the conversation before you proceed, and a regulated adviser will usually encourage that too.
Is equity release right for you? Often, the answer is no.
Equity release suits some people well. For others it is the wrong answer, and a good adviser tells them so.
It may be worth considering if
- You are 55 or over and want to stay in your home
- You have genuinely explored the alternatives below
- You understand and accept the effect on your estate
- The money meets a real need, not a passing want
- Your family know and you have talked it through
It is often not right if
- You could meet the same need another way
- You want to preserve your estate for your family
- You might want to move in the next few years
- You are being pushed toward it rather than choosing it
- You are not sure what it will cost over twenty years
Our qualified FCA-regulated partners will guide you through the available options and, where appropriate, recommend a suitable product based on your circumstances and requirements. That includes weighing the alternatives with you and telling you if equity release is not the right answer.
We may receive a referral payment from our partner. This will not normally affect the amount you pay, and any fee payable directly by you will be disclosed and agreed before you proceed. See our terms of use for the detail.
The alternatives to consider first.
A proper advice process weighs these against equity release for your actual situation. If one of them is better for you, that is what you should be told.
- Downsizing. Selling and moving somewhere smaller releases equity without a compounding loan attached to it. Emotionally harder, financially often cleaner.
- A retirement interest-only mortgage. Known as a RIO. You pay the interest monthly, so the debt does not roll up and does not compound. You need to be able to afford the payments.
- Conventional borrowing, if it is affordable and the sum is modest.
- Savings, investments or pensions you could draw on before borrowing against your home.
- Support from family, particularly where the family is the intended beneficiary of the estate anyway. An awkward conversation is cheaper than compound interest.
- Grants or benefits you may be entitled to but are not claiming. A significant number of people release equity to cover a shortfall that an unclaimed entitlement would have met.
How much does it cost? Compound interest explained.
The cost is not just the interest rate. It is what compounding does to that rate over time.
Say you release fifty thousand pounds and make no payments. The interest for the first year is added to the loan. In the second year, interest is charged on the larger amount, and that is added too. And so on. Over fifteen to twenty years, the total owed can be two to three times what you originally borrowed, depending on the rate and how long it runs.
That is not a scare tactic, it is arithmetic, and it is the reason equity release needs advice rather than a website. It is also why the age you start matters so much: the same loan taken at 60 compounds for far longer than one taken at 78.
You can reduce or stop the roll-up by making voluntary interest payments, which many modern products allow. A good illustration shows you both scenarios side by side.
We do not publish rates for equity release. Rates on a regulated product belong with the advice, and a rate without a suitability assessment is not useful to you. Ask for a personalised illustration: it shows the real numbers for your situation, including the projected roll-up, and you should have one before you proceed with anything.
Effect on benefits, tax and inheritance.
Benefits
The cash you release counts toward means-tested benefit assessments. Releasing equity could reduce or remove entitlement to Pension Credit, Council Tax Support and others. Check your own position before you commit, and consider free guidance from Citizens Advice or MoneyHelper alongside regulated advice.
Tax
The cash released is not itself taxed as income. But what you do with it, and the effect on your estate, can have tax consequences. This is a question for an accountant or tax adviser, not for us and not for a web page.
Inheritance
This is the big one for most families. Equity release reduces your estate and therefore what you can leave. Some products offer inheritance protection, guaranteeing a set portion of your home's value for your family regardless of how the loan grows. If leaving something matters to you, say so early, because it changes which products are suitable.
How it works.
That you are considering equity release
We give you honest general information: this page, and a straight conversation about whether it is even the right question.
One of our qualified FCA-regulated partners
A no-obligation call, at a time that suits you, with an adviser who specialises in equity release and later-life lending.
By a qualified, FCA-regulated adviser
A qualified adviser assesses your circumstances, weighs the alternatives with you, and recommends equity release only if it is genuinely suitable.
In your own time
Nothing is committed until you say so. You get a personalised illustration setting out the features, the costs and the risks before anything goes ahead.
Hunter Grey is not authorised or regulated by the Financial Conduct Authority. The regulated advice and the recommendation are our partner adviser's. Our terms of use set this out in full.
Frequently asked questions.
What is equity release?
A way for homeowners aged 55 and over to access tax-free cash from their home's value without moving out. The most common type is a lifetime mortgage, repaid when you die or move into long-term care.
How does a lifetime mortgage work?
You borrow against your home and keep living there as the owner. Interest usually rolls up and compounds rather than being paid monthly, and the loan plus interest is repaid from your home's sale when you die or move into care.
Is equity release safe?
Products from Equity Release Council members carry safeguards, including a no-negative-equity guarantee, so you will never owe more than your home is worth. But safe is not the same as right. It remains a major decision with real consequences for your estate and your benefits, and it is not suitable for everyone. Assessing whether it is right for you is what regulated advice is for.
What are the downsides of equity release?
It reduces what you leave your family, the debt compounds and can grow quickly, it can affect means-tested benefits, early repayment charges can be high, and it may limit your future options including moving.
Can I still leave an inheritance?
Equity release reduces your estate, but some products offer inheritance protection guaranteeing a portion of your home's value for your family. If this matters to you, raise it at the start, because it affects which products are suitable.
What are the alternatives to equity release?
Downsizing, a retirement interest-only mortgage, conventional borrowing, drawing on savings or pensions, support from family, or benefits you are entitled to but not claiming. A good adviser weighs these with you before recommending equity release.
Do you have to pay it back?
Not usually during your lifetime. It is typically repaid from the sale of your home when you die or move into long-term care. You can make voluntary payments to slow or stop the interest rolling up.
Who gives the advice?
Our qualified FCA-regulated partners will guide you through the available options and, where appropriate, recommend a suitable product based on your circumstances and requirements. Hunter Grey is not FCA authorised and does not give regulated advice; our terms of use explain how that works.
Does a call commit me to anything?
No. It is a conversation, nothing more. The adviser may well tell you equity release is not right for you, which is part of what regulated advice is for.
Brian Leppard, Equity Release Manager.
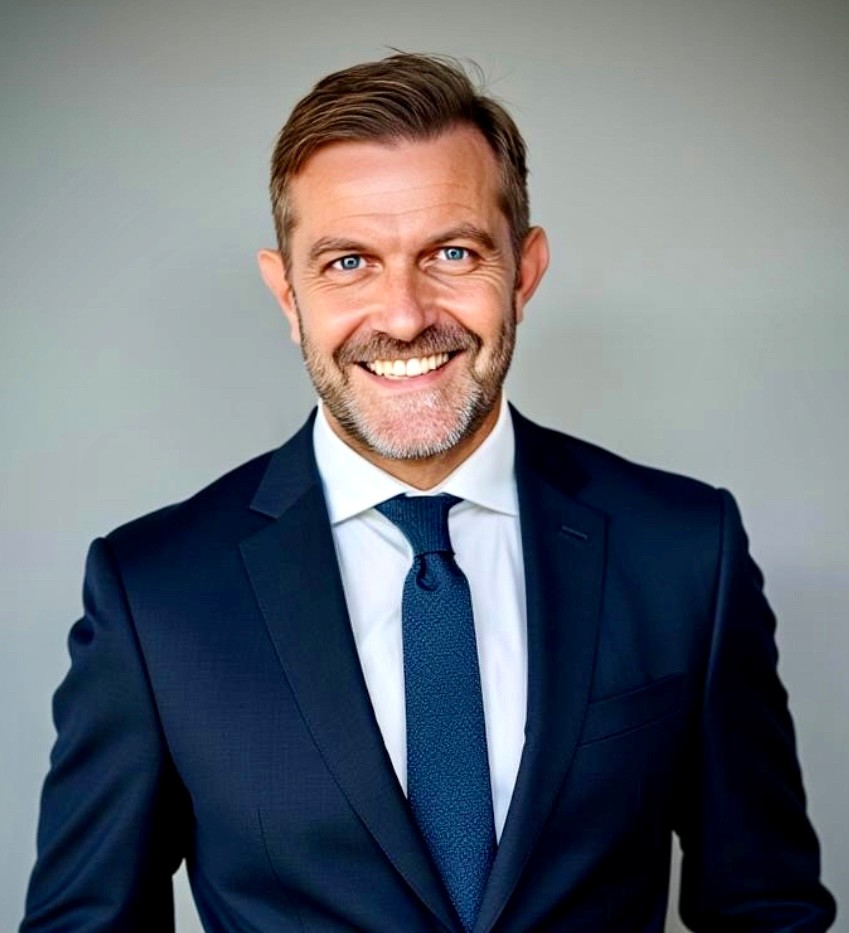
Brian has more than 25 years in property finance across the UK and Australia, and specialises in equity release, lifetime mortgages and later-life lending, helping clients understand how the wealth tied up in their homes could support them financially in later life. Whether it is supplementing retirement income, repaying an existing mortgage, helping family onto the property ladder, funding home improvements or simply enjoying more financial freedom in retirement, he gives clear, straightforward advice tailored to each client's circumstances. Known for his personal approach and long-term client relationships, Brian believes later-life lending does not need to feel complicated. His focus is on making sure clients fully understand their options, the benefits and the implications, and feel comfortable with every decision they make.
Brian is one of our qualified FCA-regulated partner advisers. He will guide you through the available options and, where appropriate, recommend a suitable product based on your circumstances and requirements.
Get a no-obligation call back.
Tell us what you are trying to achieve and we will arrange a no-obligation call back. Our qualified FCA-regulated partners will guide you through the available options and, where appropriate, recommend a suitable product based on your circumstances and requirements.